Notes
The bullwhip effect: why port container counts move before earnings do
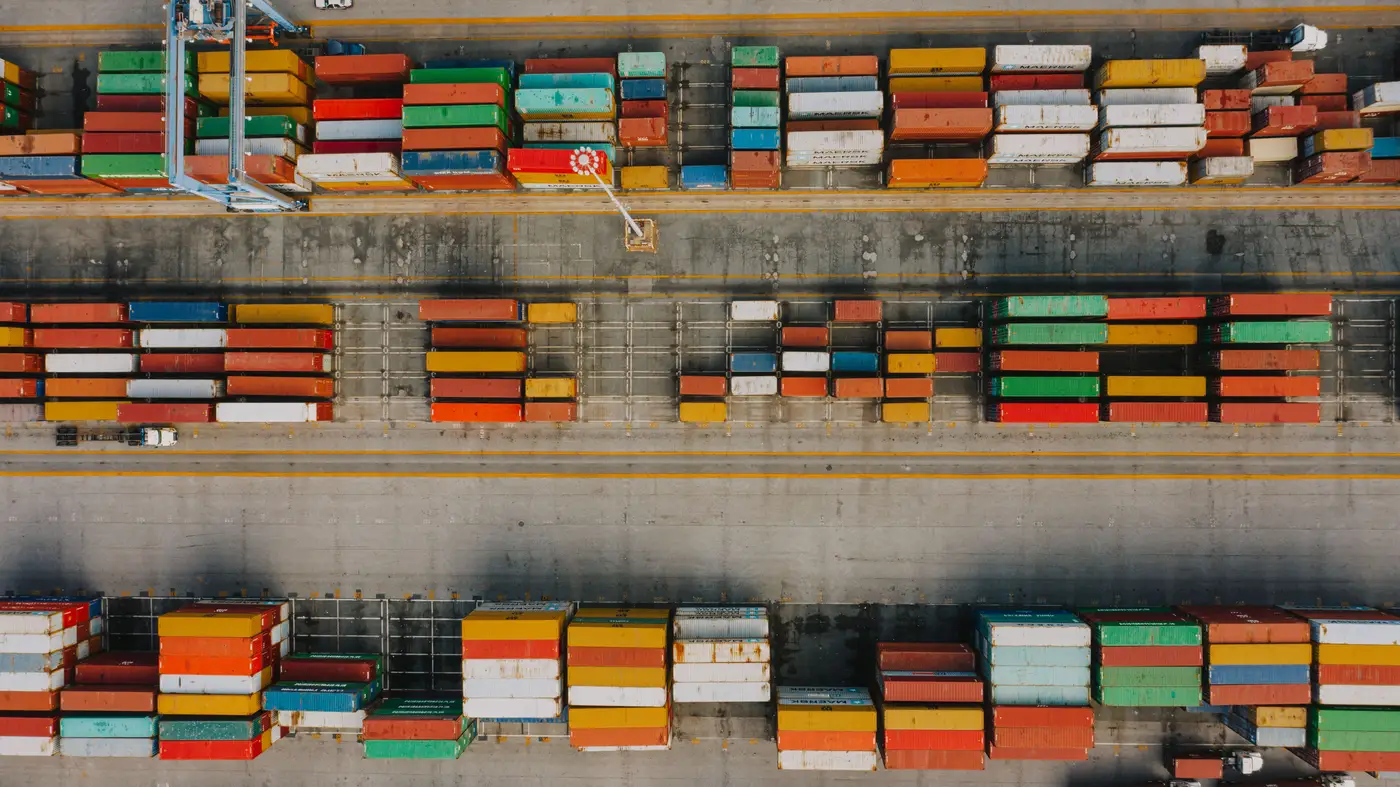
Every analyst who has sat through a retailer's inventory-glut quarter has heard some version of the same line on the call: "demand came in softer than we modeled." What usually happened three or four months earlier had nothing to do with shoppers. It happened in a container order placed by a buyer trying to guess what shoppers would want next spring.
That guessing, amplified at every link in the chain, is the bullwhip effect. A small wobble at the register turns into a much bigger wobble in factory orders by the time it has passed through store, distribution center, importer and manufacturer. Each link adds its own buffer. A buyer who gets caught short this quarter hears about it from the regional manager, so most buyers pad the order a little, and a little padding stacked across five links in the chain adds up fast.
How the whip actually builds
Start at the register. Sales dip two percent below plan for a few weeks. The store manager doesn't want to run out, so the reorder to the DC goes up, not down, just in case the dip is noise. The DC sees several stores doing this at once and rounds its own order to the importer upward again, partly to cover safety stock, partly because lead times mean a stockout now costs more than a markdown later. The importer, looking at a forecast built on DC orders rather than register data, places a bigger container booking than the original two percent dip would ever justify. By the time that signal reaches a factory in Vietnam or a vessel string out of Ningbo, a minor softening in consumer demand has become a double-digit swing in booked TEUs.
Run it in reverse and you get the glut. Demand ticks up, everyone overcorrects on the way up, inventory piles up at the DC, and then the next quarter's orders get slashed hard to work it off, usually well past where actual demand ever moved. That's the pattern behind the blank sailings and the canceled bookings you see announced with almost no warning. The order volume itself carried the warning, weeks before any earnings call did.
Lead time is why this gets worse in ocean freight specifically. A retailer reacting to a domestic trucking delay can adjust in days. A retailer reacting to a container booked six to eight weeks out, on a vessel that takes another three to five weeks to cross, is making a call today based on a forecast of what shelves will look like two months from now. Every extra week of lead time gives the signal more room to distort before it corrects.
Where port counts fit into this
Vessel call volume, container stack height on the yard, and anchorage queue length at a given port are downstream of the order, not of the sale. By the time a retailer's quarterly inventory-to-sales ratio shows the drawdown, or a customs release confirms the import drop, the order that caused it was placed and shipped months prior. The container stacks at the origin port and the vessel calls at the destination port already carried that signal before either filing existed.
Port-level counts carry this signal before the data releases that summarize it later ever post. A string of smaller vessel calls into a corridor, or a yard that's running lighter than its seasonal norm, is the order book talking. A quarter later, that same pattern shows up as "demand came in softer than we modeled." A daily feed built from container stacks, vessel calls and anchorage queues at named ports reads that order-book signal while it's still forming, before a retailer gets the chance to explain it away on a call.
None of this requires guessing at the magnitude of the swing ahead of time. It means watching the layer of the chain where the distortion shows up first, which is cargo movement, not inventory commentary. If you're trying to get ahead of a glut or a shortfall before the sell-side does, that's the layer worth checking daily rather than quarterly.
Trade Flow Index runs that daily count so the order-book signal doesn't wait for a press release to reach you.